
Inventory shrinkage is the gap between the stock your records say you have and the stock actually on the shelf — inventory that has been lost to theft, error, damage, or fraud. It is measured as a percentage of sales or inventory value, and it comes straight off your bottom line, because you paid for goods you can no longer sell. This guide explains what inventory shrinkage is, how to calculate it, what causes it, what an acceptable rate actually looks like, and the practical steps that actually reduce it in a warehouse.
What Is Inventory Shrinkage?
Inventory shrinkage is the loss of inventory between the point it is recorded in your system and the point it is sold or shipped. If your books show 1,000 units but a physical count finds 970, the missing 30 units are shrinkage. It represents real money lost — the cost of goods you owned, tracked, and expected to sell, but no longer have.
Every business that holds stock has some shrinkage. The goal is not zero — that is unrealistic — but keeping it low and understanding where it comes from, so you can stop the causes you control.
Shrinkage is not the same as obsolescence or a routine write-down. Obsolete stock is still physically present and still counted; it has simply lost its value because demand moved on. A write-down reduces the carrying value of goods you still hold. Shrinkage means the units are not there at all, or are no longer sellable in any form. The distinction matters because the fixes are unrelated: obsolescence is a buying and forecasting problem, while shrinkage is a control problem inside the four walls.
How Do You Calculate Inventory Shrinkage?
The inventory shrinkage rate is simple to calculate:
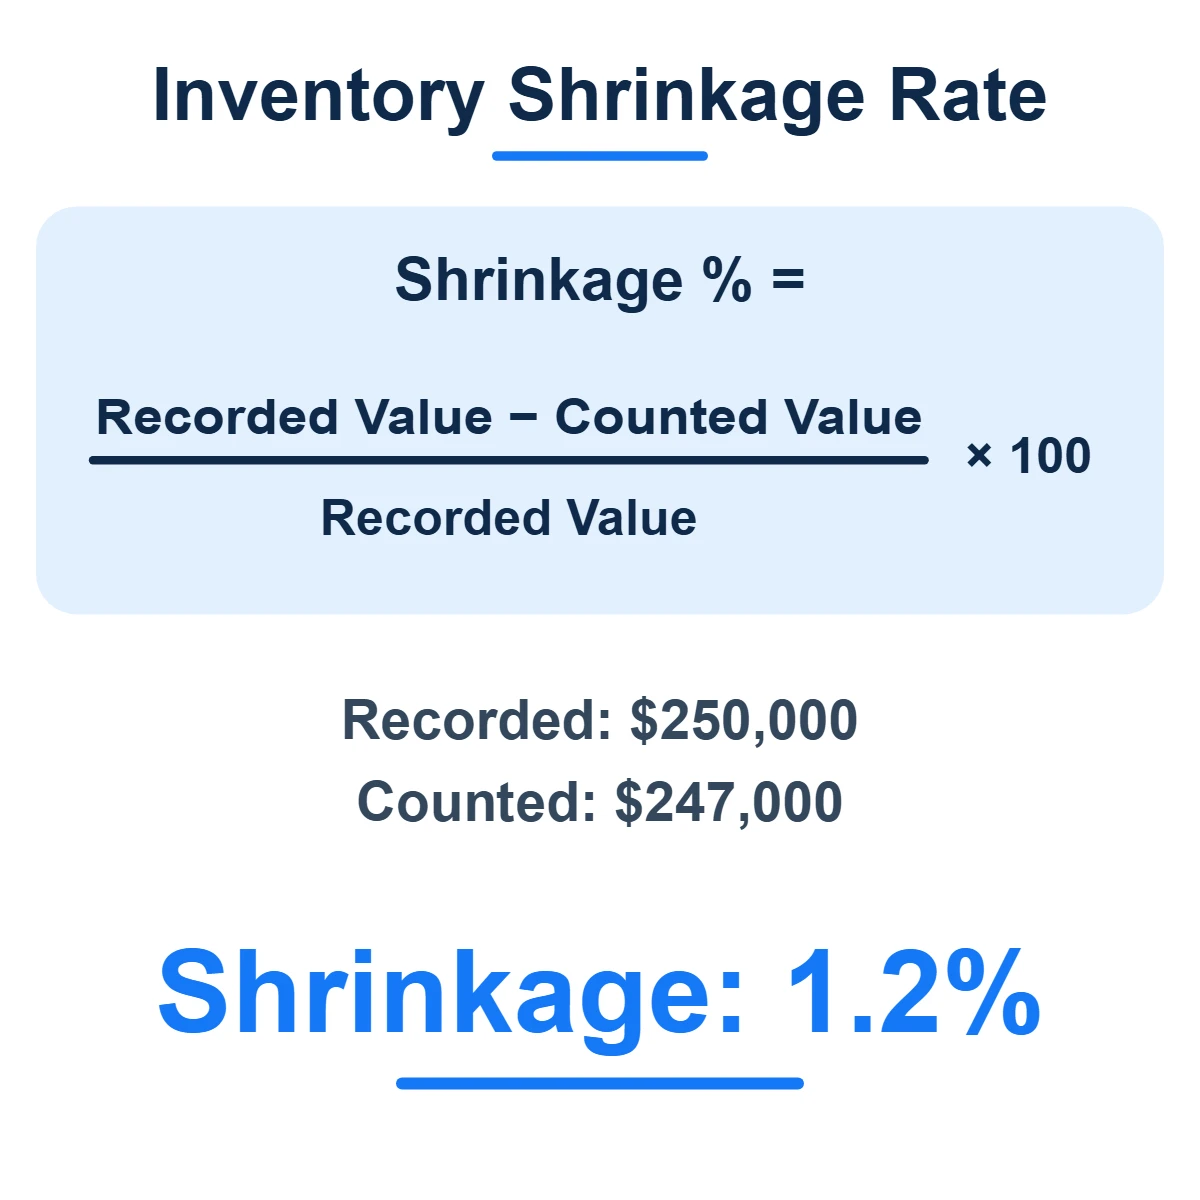
Shrinkage rate = (Recorded inventory value − Actual counted inventory value) ÷ Recorded inventory value × 100
The same count supports three measures, and they answer different questions. In units, shrinkage is the recorded count minus the actual physical count, which tells you how many items are missing. In value, it is recorded book value minus actual counted value, which tells you what the loss cost. As a percentage, it is the value figure divided by recorded book value, multiplied by 100, which is the form used for trending and comparison. Units point you at a specific SKU to investigate; value and percentage are what finance and management act on.
For example, if your records show $250,000 of inventory but a physical count finds $247,000, the shrinkage is $3,000, or a 1.2% shrinkage rate. You can also calculate it against sales instead of inventory value; either works, as long as you stay consistent so you can track the trend over time. You can only calculate shrinkage by comparing book stock to a physical count — which is why regular counting is the foundation of controlling it.
What Causes Inventory Shrinkage?
Inventory shrinkage traces back to five causes: administrative and process error, internal theft, external theft, damage and spoilage, and supplier error. Each needs a different control, and the mix differs sharply between a retail store and a warehouse.
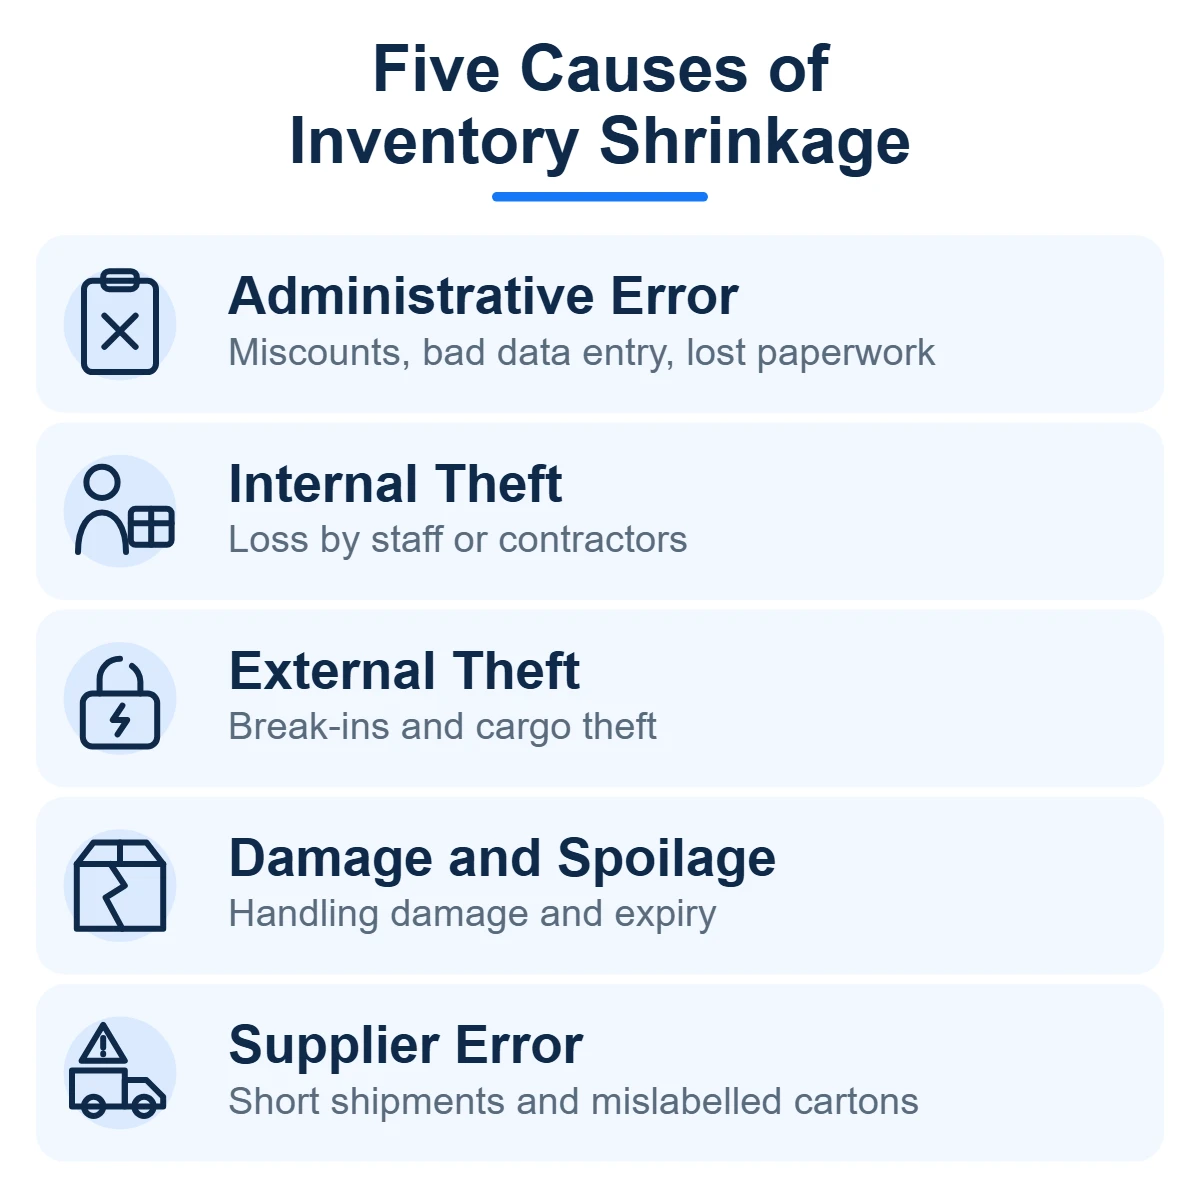
The mix decides where effort belongs, and it is not the same everywhere. In retail, theft dominates: the National Retail Federation reported that “internal and external theft accounted for nearly two-thirds (65%) of retailers’ shrink” in FY 2022. A warehouse inverts that emphasis. With no public footfall, sealed unit loads and controlled access, its losses concentrate in administrative error and damage, which are process problems rather than security problems, and process problems are the cheaper kind to fix.
| Cause | What it looks like | Primary control |
|---|---|---|
| Administrative error | Miscounts, mis-scans, receiving mistakes | Scan at every touchpoint, cycle counting |
| Internal theft | Stock leaves without a record | Access control, segregation of duties, audit trails |
| External theft | Losses at dock or in transit | Seals, camera coverage, carrier accountability |
| Damage and spoilage | Written off rather than sold | Handling standards, racking condition, FIFO rotation |
| Supplier error | Short shipments accepted as complete | Verify inbound against the purchase order |
Administrative and Process Error
Administrative error is stock that was never lost at all, only recorded wrongly: miscounts, mis-scans, the wrong unit of measure, a pallet booked to the wrong location, or paperwork that never matched what physically moved. In a controlled warehouse this is the cause that produces the most variance, because every transaction is a chance to record something incorrectly. It is also the most fixable, since the fix is process and scanning discipline rather than surveillance.
Internal Theft
Internal theft is stock removed by people who already have legitimate access to it. It is harder to detect than external theft because the person taking the goods can often also adjust the record, which is why separation of duties matters more here than cameras. The control is structural: limit who can move stock, limit who can approve an adjustment, and make sure those are never the same person for the same zone.
External Theft
External theft is loss at the dock, in transit, or through fraudulent collection. A warehouse has far less exposure to it than a retail store, because there is no public footfall and goods move in sealed units. The controls are physical and contractual: seals checked against paperwork at both ends, camera coverage of every dock door, and carrier accountability written into the agreement rather than assumed.
Damage and Spoilage
Damage and spoilage is stock written off because it was broken in handling or expired before it shipped. It differs from the other causes in that the goods are still physically present, just unsellable, so it often goes unrecorded until a count forces the issue. Handling standards, racking condition and strict FIFO rotation control it; a damage log that nobody fills in does not.
Supplier and Vendor Error
Supplier error is shrinkage you inherit rather than create: short shipments signed for as complete, cartons labeled with the wrong SKU, or invoices for goods that never arrived. It shows up as a variance weeks later in your building, which is why it is so often misattributed to internal causes. Verifying inbound against the purchase order at the dock is the only place this is cheap to catch.
What Is an Acceptable Inventory Shrinkage Rate?
There is no published warehouse shrinkage benchmark, so an acceptable rate is one that is low, stable, and trending down against your own baseline rather than against an industry figure. The number most often quoted is retail data, and applying it to a warehouse will mislead you.
The National Retail Federation put average retail shrink at 1.6% of sales in FY 2022 in its 2023 National Retail Security Survey, up from 1.4% the year before and worth $112.1 billion across the industry. That figure describes retail stores, where shoplifting is the dominant cause. A warehouse has no public footfall, moves goods in sealed units, and controls who enters, so its profile tilts toward administrative error and damage instead. Borrowing 1.6% as a warehouse target sets the bar in the wrong place and against the wrong causes.
Set your own benchmark instead. Calculate shrinkage the same way for four consecutive quarters, treat the average as your baseline, then judge every subsequent period against it. A rate that holds steady or falls is healthy at almost any absolute level; a rate climbing above your own baseline is a signal worth investigating regardless of how it compares to anyone else. Track it alongside inventory accuracy and the rest of your warehouse KPIs, because a shrinkage number with no target attached is just reporting.
How Do You Reduce Inventory Shrinkage?
Disciplined process prevents most of the shrinkage a warehouse actually controls. The steps that make the biggest difference:
- Count regularly with cycle counting. Counting a portion of SKUs continuously catches discrepancies early, while they are still traceable, instead of once a year when the trail has gone cold.
- Scan at every touchpoint. Barcode or RFID scanning at receiving, put-away, picking, and shipping removes the manual-entry errors that produce administrative shrinkage.
- Tighten receiving. Verify every inbound shipment against the purchase order and inspect for damage before it enters stock — a receiving error contaminates every later count.
- Keep inventory accurate in real time. A single, live view of stock means a discrepancy shows up immediately, not months later.
- Control access and separate duties. Limit who can move or adjust stock, and make sure the person counting is not the only person recording — this deters and catches internal theft and fraud.
- Investigate every variance. Treat each count discrepancy as a lead. Patterns by SKU, shift, or location point straight to the cause.
- Track shrinkage as a KPI. What you measure and review gets managed; what you ignore grows quietly.
Where Does Shrinkage Hide in a Warehouse?
Shrinkage concentrates in four places: the receiving dock, bulk and reserve storage, the returns and reverse-logistics area, and any location that equipment cannot easily reach. These are the points where stock changes hands, changes status, or sits undisturbed long enough for an error to age past the point of tracing.
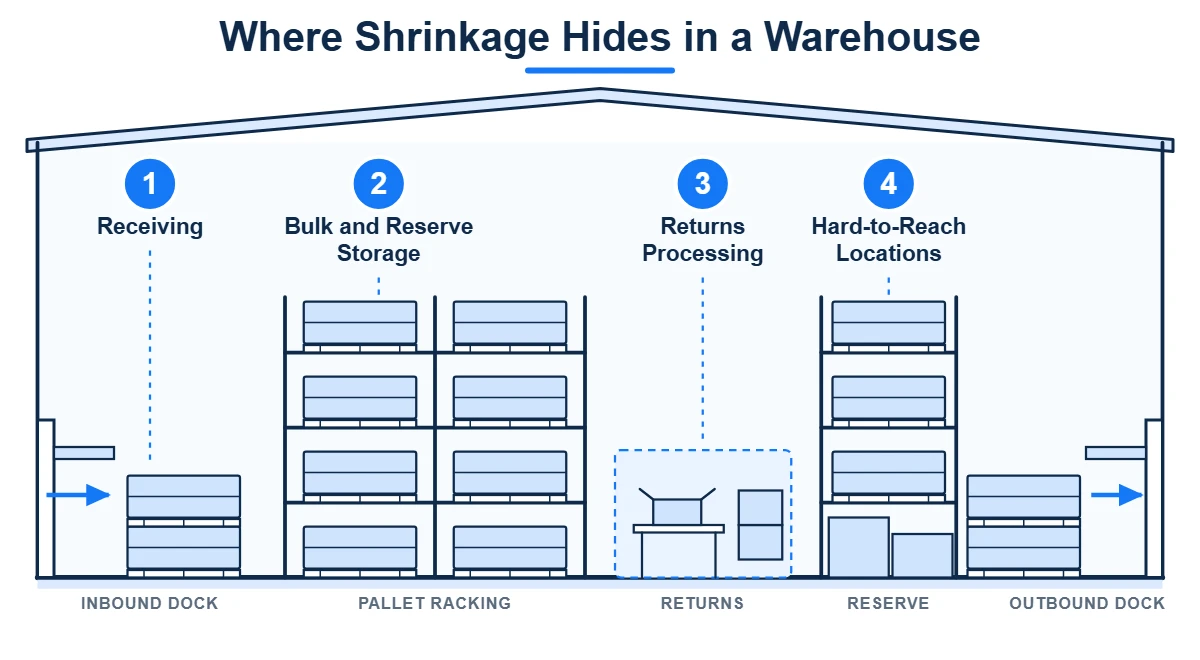
Receiving. Every downstream number inherits whatever happens here. A short shipment signed for as complete, a mis-scanned SKU, or a pallet booked to the wrong location becomes a variance that surfaces weeks later somewhere else entirely, with no obvious link back to the dock.
Bulk and reserve storage. High racking and overflow areas get counted least because counting them needs equipment and a spotter. Errors there survive longest, and by the time a count reaches them the transaction history that would explain the variance has usually rolled off.
Returns and reverse logistics. Returned goods arrive outside the normal receiving flow, often without a matching record, and sit in a staging area waiting for a disposition decision. Stock in that state belongs to no one, which is exactly when it disappears or gets written off twice.
Hard-to-reach locations. Anything requiring a reach truck, a ladder, or moving another pallet first gets skipped when counts run behind schedule. Nothing routinely disturbs those bins, so nothing routinely corrects them either.
How Do You Investigate a Shrinkage Variance?
Investigate a variance by recounting first, then tracing the transaction history for that SKU and location, assigning a reason code, and fixing the process that produced it. Adjusting the record without doing this corrects the number and leaves the cause running, which is why the same variance reappears at the next count.
Recount before you believe it. Counting errors are common enough that a single count disagreeing with the system is a question, not a finding. A second count by a different person confirms whether the variance is real.
Trace the transactions. Pull every movement for that SKU and location since the last confirmed-correct count: receipts, put-aways, picks, replenishments, adjustments and returns. Most variances have a specific event behind them, and it is usually visible in the sequence.
Assign a reason code. Use a fixed list — receiving error, pick error, damage, mislocation, unrecorded scrap, supplier short — so that variance data can be analyzed later. Free-text notes cannot be aggregated, so a year of them tells you nothing.
Look for the pattern, not the incident. One variance is noise. The same reason code recurring by zone, by shift, by SKU family or by individual is a process fault with an address. Review those patterns monthly rather than case by case.
Fix upstream, then re-measure. Change the process that produced the variance, then watch whether the reason code stops appearing. If it does not, the diagnosis was wrong and the investigation is not finished.
How Is Inventory Shrinkage Recorded in Accounting?
Inventory shrinkage is recorded by writing the inventory asset down to the counted quantity and booking the difference as an expense. The entry debits a shrinkage expense account or cost of goods sold and credits inventory, which removes the value of goods you no longer have from the balance sheet and recognizes the loss in the period the count found it.
Whether the debit goes to cost of goods sold or to a separate shrinkage expense account is a visibility decision rather than a technical one. Folding it into cost of goods sold keeps the accounts simple but buries the number, so nobody sees it move. Booking it separately makes shrinkage a line somebody has to explain each period, which is usually what changes behavior.
Timing matters as much as treatment. If the only count is annual, the write-down lands as a single large adjustment with no traceable cause, and the finance team learns about a problem the warehouse could have caught in March. Counting continuously spreads the recognition across periods and keeps each adjustment small enough to explain.
The operational point is that shrinkage is real spent money, not a rounding error. Every unit written off was paid for, handled, stored and will never generate revenue, which is why prevention spending is measured against the write-off it avoids rather than against zero.
Inventory Shrinkage in B2B and Wholesale Warehousing
In B2B and wholesale warehousing, shrinkage is counted at pallet and case level, must account for lot and expiry status as well as quantity, and often involves stock the warehouse does not own. Most published guidance describes retail shelves or direct-to-consumer ecommerce, where units are identical and counted in eaches, and several of those assumptions do not hold.
Pallet and Case Level Loss
Wholesale stock moves in pallets and cases, so a single shrinkage event is larger and rarer than in a retail environment. One mis-shipped pallet can outweigh a year of small discrepancies, which means average shrinkage rates hide more than they reveal. Track variance value alongside variance count, because twenty small errors and one lost pallet look similar on a percentage chart and are not remotely the same problem.
Lot, Batch and Expiry Status
For food, pharmaceutical, chemical and regulated goods, stock can be quantity-accurate and still worthless. A location holding the right number of units under the wrong lot number, or past its expiry date, will fail a shipment or trigger a recall while passing a count that checks only quantity. Expiry write-offs are shrinkage, and they belong in the same number as theft and error rather than in a separate report.
Who Absorbs the Loss on Client-Owned Stock?
In a third-party warehouse the loss falls wherever the contract says it falls, because shrinkage is being measured against stock the operator does not own. That makes write-off authority a contractual question rather than an internal one: confirm in writing who may authorize a write-off against your inventory and what variance reporting you receive. The counting and adjustment mechanics behind those numbers are covered in our cycle counting guide.
How a 3PL Helps Control Shrinkage
A third-party warehouse controls shrinkage through built-in process rather than added effort: scanning at every touchpoint, continuous cycle counts, controlled access, and a warehouse management system holding a live view of every unit. In the operations we run, those controls are what keep the shrinkage number small and, more importantly, explainable. For a growing brand, outsourcing to a fulfillment center that already runs them is often faster than building the same discipline in-house.
If you are evaluating providers, the questions worth asking are specific: how often is my stock counted, are counts blind, what is the documented variance tolerance, who may approve an adjustment to my inventory, and what shrinkage reporting will I receive. A provider that cannot answer those precisely does not have a controlled program, whatever the sales deck says.
Cura Resource Group runs cycle counting against a live WMS record rather than one annual full count, which is what keeps shrinkage visible while the cause is still traceable. A discrepancy found in March can usually be explained; the same discrepancy found in December almost never can. Our inventory control services cover the counting, scanning and access discipline that keeps the number low, and you can request a quote to see how we report it.
Final Word
Inventory shrinkage is money you already spent walking out the door — through theft, error, damage, or fraud. You cannot eliminate it, but you can keep it low: calculate it honestly against a physical count, learn your mix of causes, and attack the biggest one with disciplined counting, scanning, receiving, and access control. Track the trend, investigate every variance, and shrinkage moves from an invisible drain to a number you control.
Want fulfillment with shrinkage control built in?
Frequently Asked Questions
What Counts as Inventory Shrinkage?
Inventory shrinkage is the difference between the stock your records show and the stock physically present, caused by theft, administrative error, damage, or supplier fraud. It is a real financial loss because you paid for goods you can no longer sell.
How Do You Calculate the Inventory Shrinkage Rate?
Subtract the actual counted inventory value from the recorded value, divide by the recorded value, and multiply by 100. For example, $250,000 recorded minus $247,000 counted is $3,000, a 1.2% shrinkage rate. You need a physical count to calculate it.
Where Does Most Inventory Shrinkage Come From?
The five causes are administrative and process error, internal theft, external theft, damage and spoilage, and supplier error. The National Retail Federation put internal and external theft at 65% of retail shrink in FY 2022, but a controlled warehouse sees more administrative error and damage because it has no public footfall.
How Much Shrinkage Is Normal for a Warehouse?
There is no published warehouse benchmark. The often-quoted 1.6% comes from the National Retail Federation 2023 survey and describes retail stores, where shoplifting dominates. Judge a warehouse against its own trailing four quarters instead: a stable or falling rate is healthy, and one climbing above your baseline needs investigating.
What Is the Fastest Way to Cut Shrinkage?
Cycle count regularly instead of waiting for one annual count, scan at every touchpoint so movements are recorded rather than remembered, verify inbound shipments against the purchase order at receiving, restrict access to high-value stock, and reconcile discrepancies while the cause is still traceable.
How Do You Record Inventory Shrinkage in Accounting?
Write the inventory asset down to the counted quantity and book the difference as an expense: debit shrinkage expense or cost of goods sold, credit inventory. Booking it to a separate shrinkage account rather than burying it in cost of goods sold makes the number visible enough that somebody has to explain it.
Is Inventory Shrinkage the Same as Inventory Variance?
No. Variance is any gap between recorded and counted stock, including gaps later explained and corrected. Shrinkage is the portion that represents genuine loss, meaning goods gone for good through theft, error, damage or fraud. Every shrinkage figure starts as a variance; not every variance becomes shrinkage.
Who Is Responsible for Shrinkage in a Third-Party Warehouse?
The stock belongs to the client, so the warehouse carries the accuracy obligation without owning the goods. Adjustment authority is contractual rather than assumed. Confirm in writing who may authorize a write-off against your inventory, what the reporting cadence is, and how disputed variances get settled.
Sources & Further Reading
- National Retail Federation, 2023 National Retail Security Survey — retail shrink rate, FY 2022.
- National Retail Federation press release, September 2023 — theft as a share of retail shrink.